
Payday Loans AL Rules, Fees and Safer Choices
Alabama's legal limits on payday loan balances and fees set a boundary, not a measure of affordability. The detailed limits table below shows what licensed lenders may offer. Staying within those rules does not mean the repayment will fit your budget.
The key question is what remains after payday. Add the full amount due to the rent, food, utilities, gas, and other debits you already expect. If paying the loan leaves too little for those expenses until your next paycheck, the legal ceiling has not made the loan manageable.
Before borrowing, check whether your paycheck can cover the full balance and fee while leaving enough for essentials.
A limit is like a marked lane on a road: it sets a boundary, but it does not tell you whether the journey is safe for your budget.
Table of Contents
- Payday Loans AL Limits and Fees at a Glance
- How Alabama Tracks Payday Loans
- What Repeat Payday Loans Cost in Fees
- A Paycheck Test Before You Borrow
- Cheaper Options Than an Alabama Payday Loan
- When a Payday Fee or Debit Goes Wrong
- Decide and Request Only If the Paycheck Clears
Payday Loans AL Limits and Fees at a Glance
A legal payday loan can still leave too little for the rest of the month. Alabama's limits define what a licensed lender may offer; your paycheck determines whether you can repay it and still cover rent, food, and bills.
The rule that matters most: Check what remains after the full balance and fee come out of your next paycheck.
| Rule | Alabama limit | What it means on a loan |
|---|---|---|
| Outstanding balance | $500 across licensed lenders | A second loan cannot push the open balance over $500 |
| Maximum fee | 17.5% of the amount advanced | $87.50 on $500, or $52.50 on $300 |
| Amount due at payoff | Advance plus fee | $587.50 on $500, or $352.50 on $300 |
| Term length | Generally 10 to 31 days | The full balance is due in one short window |
| Cooling-off after two loans | Next business day | No same-day third loan after two paid in a row |
| Lender check | Statewide database | The lender must verify the cap before issuing |
Read the fee in dollars first
Alabama's framework permits a maximum fee of 17.5% of the amount advanced, with loan terms generally ranging from 10 to 31 days, according to the CFPB payday lending report. The $87.50 fee on a $500 advance is the result of applying that 17.5% cap: $500 multiplied by 0.175. On a $300 advance, the fee is $52.50, bringing the total due to $352.50.
The fee is the amount that leaves your paycheck. APR expresses a short-term fee as an annual rate, which can help compare a payday loan with credit cards or installment loans. For your budget, though, return to the actual dollars due. A percentage cannot tell you whether enough money remains for your regular expenses.
The two limits people mix up
The $500 figure is the total outstanding balance across licensed lenders, not a separate allowance at each store or website. Before issuing a loan, a lender checks the statewide database. That shared record helps prevent a borrower from taking out another loan that would push the open balance beyond the limit.
The term is different from a longer installment schedule. A payday loan generally runs for 10 to 31 days, and the full advance plus fee comes due in that short window. If your paycheck is $1,000 and the payoff is $587.50, subtract the payoff first. The remaining $412.50 must still cover everything else due before your next check. That simple subtraction is a better affordability test than the legal cap alone.
Alabama also requires a pause after two consecutive payday loans have been paid off. You must wait until the next business day before taking another one. The pause prevents an immediate third loan, but it does not reduce the next fee or increase your income.
Before signing, write down four details from the offer: the advance, the fee, the total due, and the due date. Check that the amount and fee fit Alabama's limits and that the term matches what you were told. If an offer exceeds those limits while being presented as a state-licensed Alabama payday loan, do not proceed on that basis. Check with the Alabama State Banking Department to verify the lender's license before signing or paying anything.
How Alabama Tracks Payday Loans
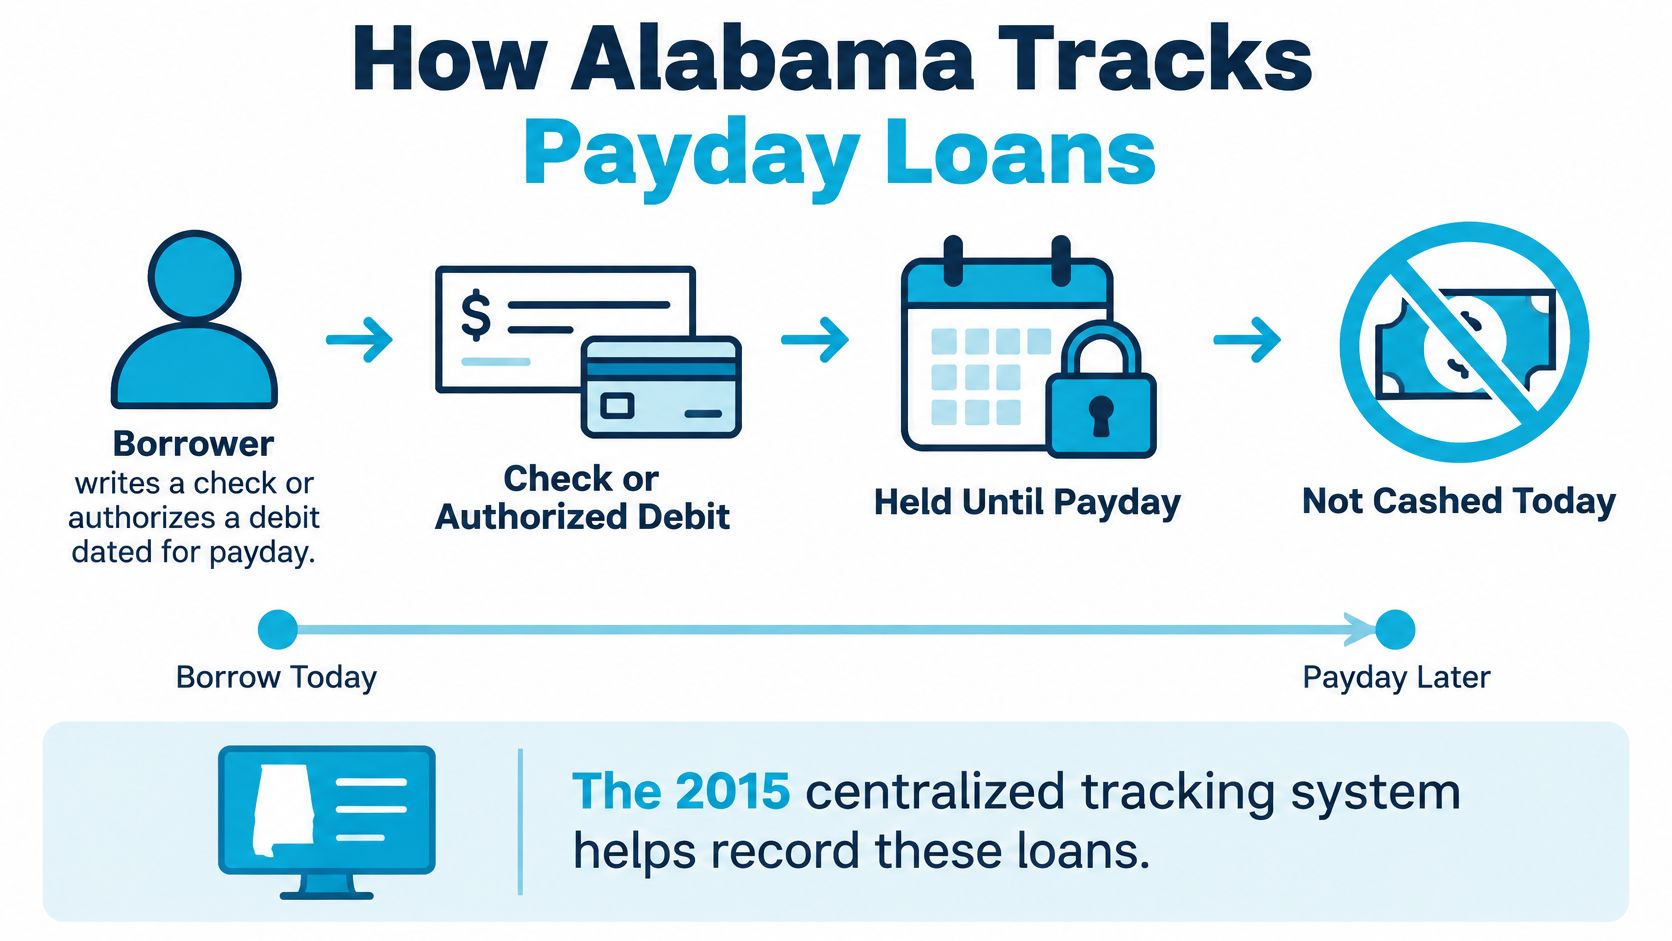
A payday loan can pass Alabama's database check and still leave too little money for rent, food, and bills after payday. The database tracks open loans against the state's cap. It cannot tell whether your next check can cover the full repayment and your regular expenses.
Why the database changed the market
A $500 limit is difficult to enforce if lenders cannot see loans issued elsewhere. Alabama created a centralized database in 2015 to help enforce its statutory $500 outstanding-balance limit, as reported by Alabama Daily News. Licensed lenders are supposed to check for open loans before issuing another one. That shared record helps prevent a borrower from taking out loans at separate stores that together exceed the cap.
The database also gives the state a way to track borrowing over time. State tracking data show that many payday borrowers take out repeat loans, and fees can add up with each new transaction. The tracking system makes those patterns visible, but it does not change the amount a borrower owes on any individual loan.
Repeat borrowing is the shape of the market
A single loan's fee may look manageable on a receipt. Several loans can mean paying a new fee each time, while still needing enough from payday income to cover the original expenses. The repeat pattern matters because a loan can fit under the legal ceiling and still be difficult to repay.
A database-cleared loan means the lender stayed inside the cap. It does not mean your household can spare the repayment.
Before applying, check the actual amount due and consider what will remain from your paycheck after rent, food, utilities, and other bills. If you are reviewing payday loan requirements, remember that meeting eligibility requirements and being able to afford repayment are different tests.
Approval only means the lender can proceed under its rules. The database does not know whether rent is due after the debit or whether you will need another advance to cover groceries. The state's system checks the legal limit. Your paycheck has to cover the household limit.
What Repeat Payday Loans Cost in Fees
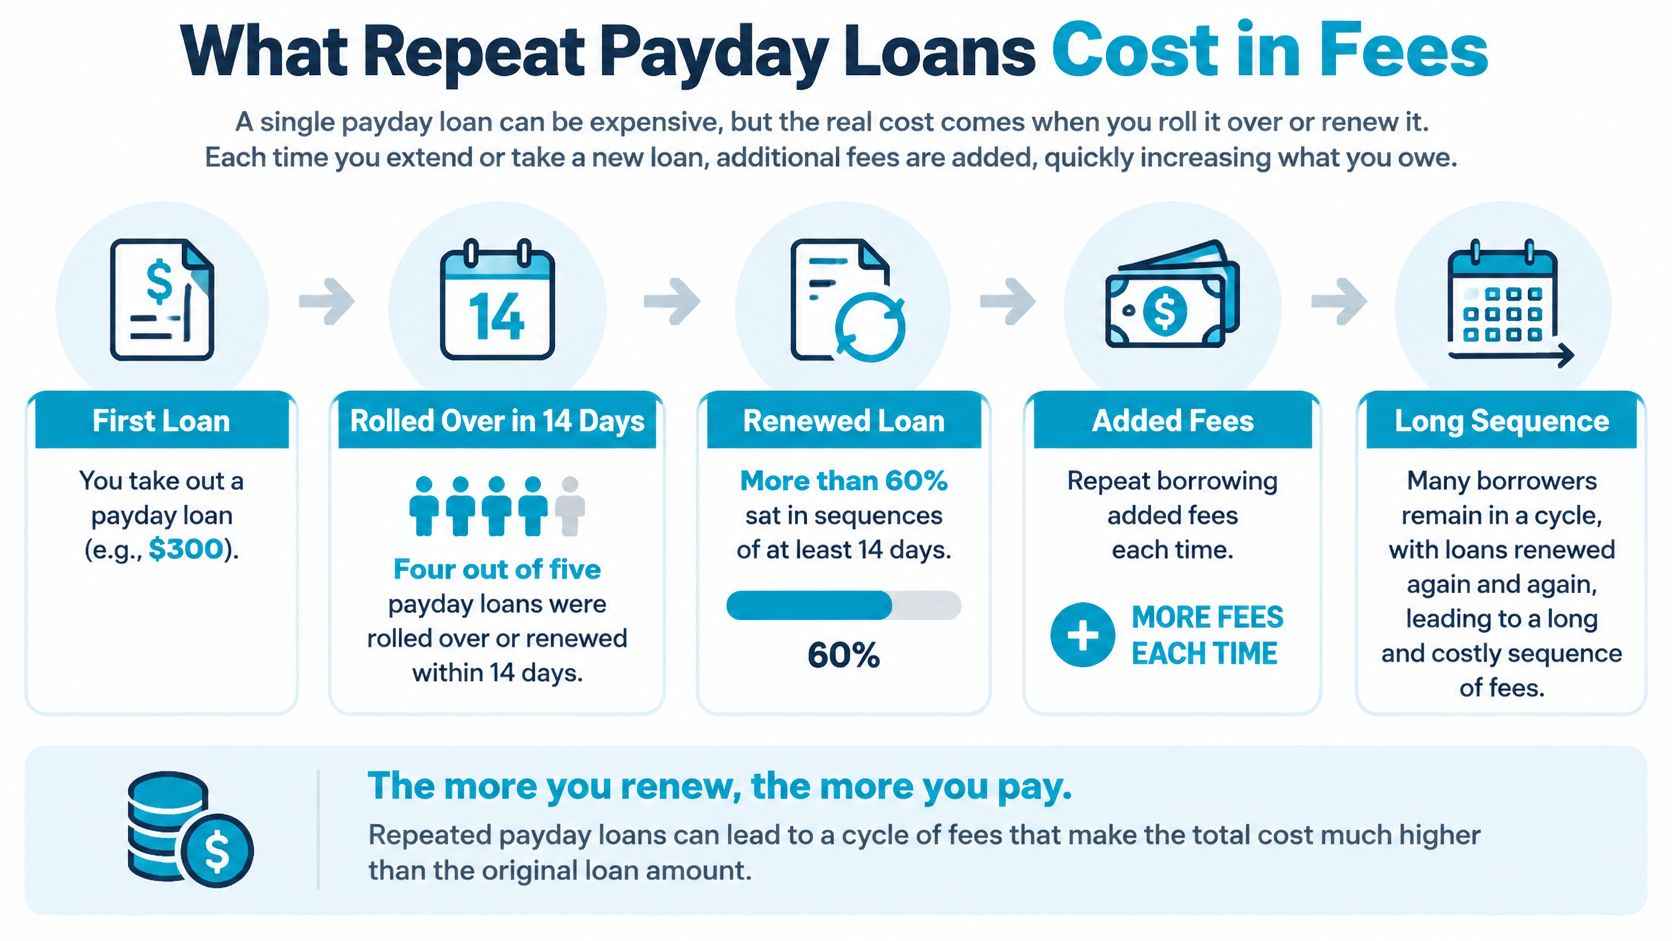
One legal loan has a price you can calculate on a napkin. A sequence of loans has a different price, and it's the sequence that traps people. The fee doesn't grow because the lender changed the rate. It grows because you pay a fresh fee each time you borrow again to cover the hole the last payoff left.
What national tracking shows about sequences
In a CFPB study tracking borrowers over 10 months, four out of five payday loans were rolled over or renewed within 14 days, according to the CFPB newsroom release on rollovers and renewals. More than 60% of loans were associated with sequences lasting at least seven loans. Roughly half of all loans occurred in sequences of 10 or more loans.
Read those figures as a pattern, not as a prediction about you personally. Most borrowers don't plan a seven-loan sequence on day one. They plan one loan, discover the payoff takes money earmarked for something else, and borrow again to cover that something else. Each step feels forced, and each step adds a fee.
Two different fee examples, so keep them separate
The CFPB illustration uses a typical fee of $15 per $100 borrowed. At that rate, a borrower who takes a $300 loan and renews it six times would incur approximately $270 in cumulative fees, which is 90% of the original principal, without reducing the principal if each renewal only extends the balance. That's national research math, useful for showing how renewals stack.
Alabama's own math uses the state cap instead. One $300 loan at the maximum costs $52.50, with $352.50 due. Pay that off and borrow $300 again, and you've bought a second $52.50 charge, then a third if you borrow a third time. If you're comparing payday loan rates, compare the total fees across the whole sequence you might realistically need, not the fee on the first loan alone.
If the only way to pay the full balance is another advance, the fee is buying time, not solving the bill.
The one-business-day pause after two consecutive paid-off loans slows that cycle by a day. It doesn't erase it. A borrower who waits until tomorrow and borrows again still owes a new fee on a new advance, and still faces the same gap between the payoff and the next paycheck.
Missed payments add another layer. Lenders may charge late fees and fees for non-sufficient funds when a debit bounces, and late payment fees are set in accordance with state regulations. Your bank can add its own charge on top of the lender's, so a failed debit can cost you twice for one missed date. Before you borrow, look at the account the debit will hit and ask what happens if a utility draft lands the same morning. If the honest answer is an overdraft, the loan's real price is already higher than the fee printed on the agreement.
A Paycheck Test Before You Borrow
Say Maya in Montgomery needs $300 for a car repair so she can get to work. A legal Alabama loan means $352.50 due, and a 14-day term annualizes to roughly 456% APR, as shown in the LendUp Alabama payday loans guide. Her next net paycheck is $1,450, which sounds like plenty until she lines up what's already promised out of it.
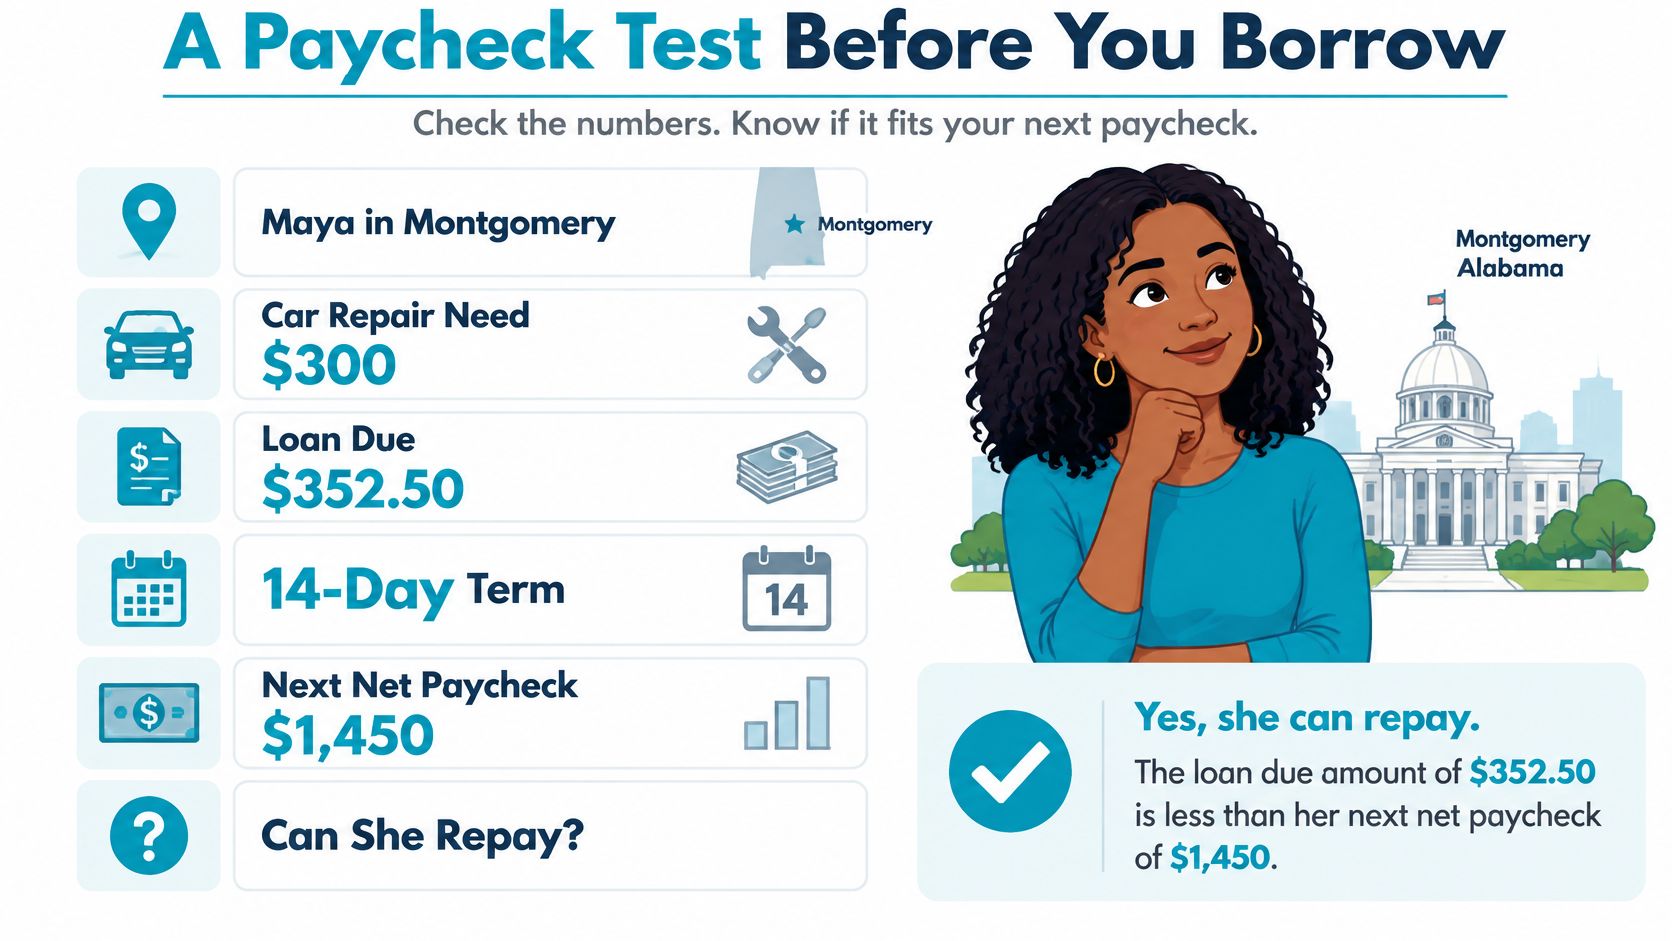
Her rent is $700 and it's due whether the car runs or not. Utilities run $180, food for the pay period is $250, gas is $120 now that the car is fixed, and an existing card payment of $90 drafts automatically. None of those numbers is careless spending. They're the cost of staying housed, fed, and employed.
| Line | Maya's amount |
|---|---|
| Take-home pay | $1,450 |
| Rent | -$700 |
| Utilities | -$180 |
| Food | -$250 |
| Transportation (gas) | -$120 |
| Existing card payment | -$90 |
| Cash left before payday loan | $110 |
| Payday-loan payoff ($300 advance plus $52.50 fee) | -$352.50 |
| Remainder after payoff | -$242.50 |
Run your own lines in the same order
Copy Maya's worksheet and replace every figure with yours. Use take-home pay, not salary, and use the actual next check if your hours vary. List rent, utilities, food, transportation, and every automatic debit that will hit before the paycheck after that, including subscriptions and minimum card payments you'd rather forget.
Then subtract the loan payoff last, in full, on its due date. Don't assume you'll pick up extra shifts, sell something, or get a refund in time unless that money is already scheduled and certain. Hope isn't a line item, and lenders don't wait because a side job fell through.
If your remainder is negative, the $500 database ceiling did not make the loan safe for you. Maya is $242.50 short, which means paying the lender in full forces her to short rent, skip a bill, overdraft the account, or borrow again. Each of those fixes creates the next problem, and borrowing again is how a single repair turns into months of fees.
Use one stop trigger and don't negotiate with it. Don't take the loan if payoff requires another advance, skipping rent, or overdrafting. Write that sentence at the top of your worksheet before you fill in the numbers, while you're still calm enough to mean it.
There is an edge case where the math works. If you have a single short gap, the full $352.50 still leaves rent, food, transport, and your other debits covered, and you won't need the same cash again next payday, a payday loan matches the job it was designed for. That's the only case where it does. If your remainder is negative, don't shrink the food line until the worksheet balances on paper. Look for a cheaper way to cover the original bill instead.
Cheaper Options Than an Alabama Payday Loan
A negative remainder on your worksheet doesn't mean you have no move. It means a lump sum due on one paycheck is the wrong shape for your problem. Work through the options below and pick the first one that pays the bill without creating a new lump sum on the same check.
| Option | How repayment works | Cost shape | Fits when |
|---|---|---|---|
| Alabama payday loan | Full balance due in 10 to 31 days | Up to 17.5% of the advance | The paycheck still covers payoff plus essentials |
| Credit union small-dollar loan | Installments for members | Often well below payday pricing | You belong to a credit union or can join one |
| Installment loan | Fixed payments over months | APR and fees set by the lender | You need time, not a single payday lump sum |
| Employer paycheck advance | Deducted from a coming check | Often no finance charge | Your employer offers it |
| Creditor hardship plan | Pause or smaller payment on the bill itself | Avoids a new loan | The crisis is one bill you can negotiate |
| Shop payment plan | Pay the repair or bill in pieces | No third-party lender | The provider will split the charge |
| Title loan | Secured by the vehicle | Can be larger; default can mean losing the car | Only if you can repay without risking transportation |
Ask before you borrow
Start with the people you already owe or already work for, because they can change a due date without selling you a loan. Call the creditor behind the bill and ask for a hardship plan, a short pause, or a smaller payment spread over the next few cycles. Ask your employer whether a paycheck advance is available and whether it's deducted once or in parts, so you don't trade one short check for another.
For Maya's repair, the shop itself may be the cheapest lender of all. Many repair shops will split a bill, hold the car an extra day while you gather part of the money, or fix the safety issue now and schedule the rest later. You won't know until you ask, and asking costs nothing.
Borrow in installments if you must borrow
A credit union small-dollar loan, often called a payday alternative loan, is designed for members who need a few hundred dollars without a two-week lump sum. Ask what you'd pay in total dollars, how many payments you'd make, and whether you can join if you aren't a member yet. An installment loan from a bank or online lender also spreads fixed payments over months, but read the APR and every fee in dollars before you sign, because a longer term can increase the total cost even when each payment looks small.
Dialing 211 or contacting a local nonprofit can surface utility, rent, or medical help that doesn't have to be repaid at all. That help takes a phone call and some paperwork, and it won't cover every expense, but money you don't borrow never charges a fee. More detail on these routes sits with payday loan alternatives if you want to compare them side by side.
Treat a title loan as a different animal, not a softer payday loan. It uses your vehicle as collateral and can be larger, but missing payments risks the car you need to earn the money to repay it. If losing the vehicle would cost you your job, the loan is risking your income to protect your income, and that trade rarely ends well.
When a Payday Fee or Debit Goes Wrong
An unexpected debit, a fee that does not match your contract, or a lender who will not provide a payoff figure calls for records and a clear process. A complaint does not cancel a valid debt or guarantee a refund. Continue addressing any amount you do not dispute while the complaint is open.
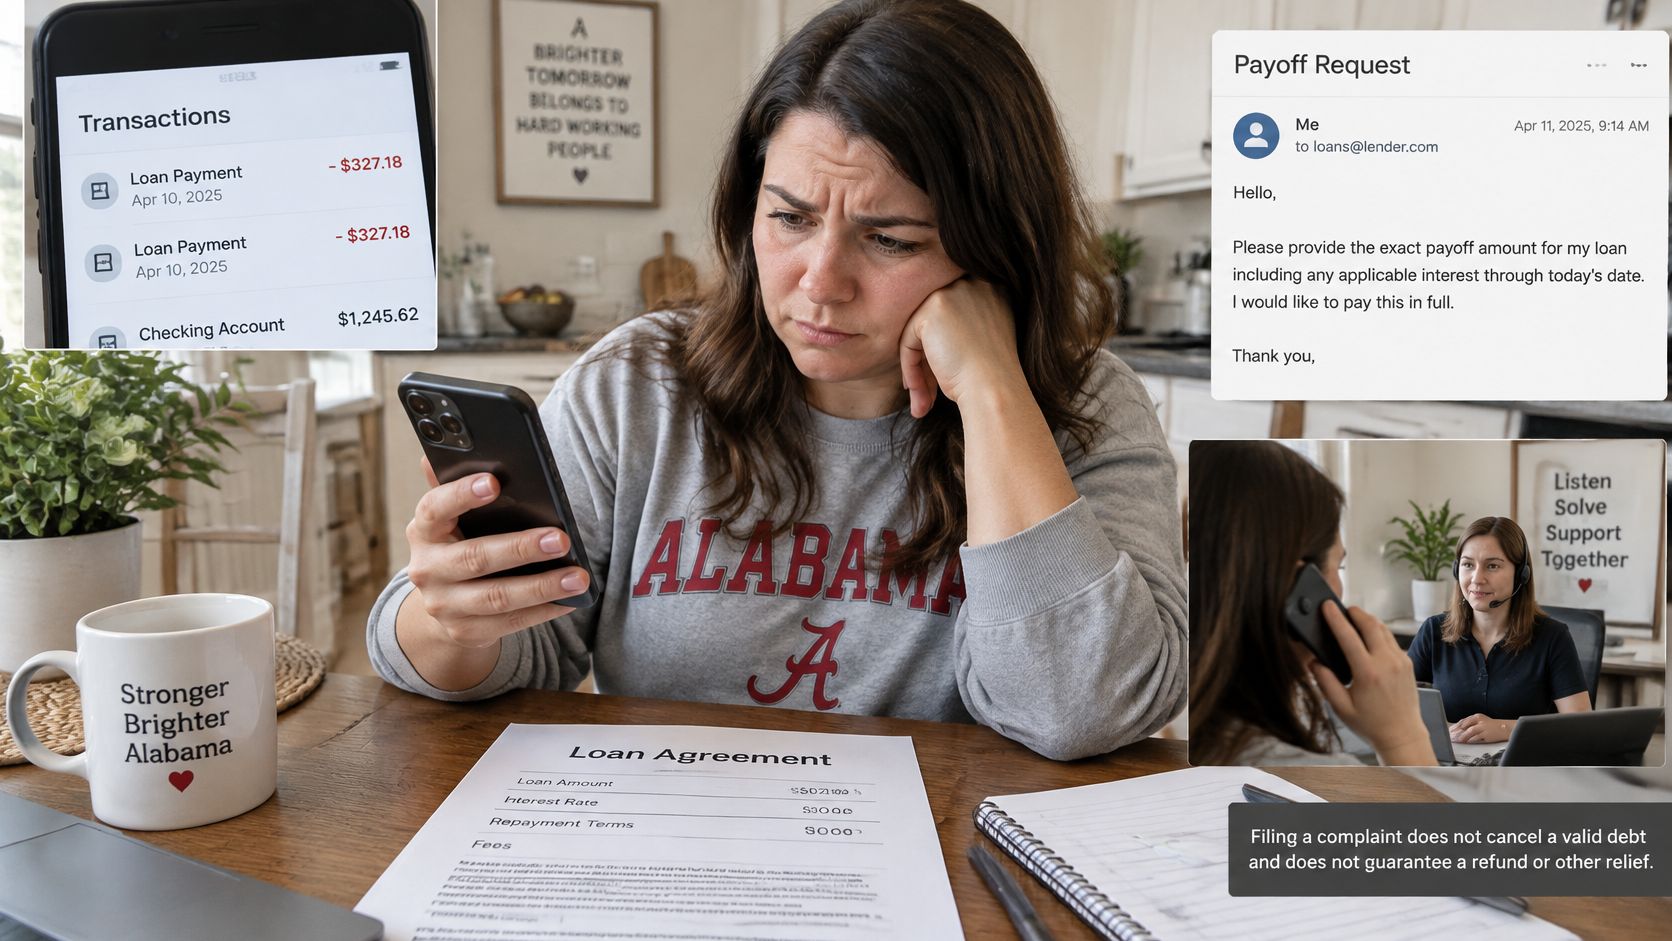
Escalate in this order
- Save everything first. Put the agreement, receipts, bank records, texts, and screenshots together before contacting the lender or a regulator.
- Identify the licensed company. Use the legal entity named in your contract, not just the brand shown on a website or storefront.
- Request written figures. Ask for the payoff amount and a full account ledger. Compare each charge with the agreement so you can identify what is disputed.
- Contact your bank about a disputed debit. If an electronic withdrawal was unauthorized or continued after you revoked authorization, tell your bank promptly and keep the confirmation number.
- File with the state banking regulator. The Alabama State Banking Department complaint page accepts complaints involving payday lenders through its Consumer Affairs or Consumer Lending channels.
- Contact the Attorney General about deceptive conduct. Alabama's Attorney General has a consumer-complaint process and hotline for problems that appear deceptive rather than simple billing errors.
The CFPB and state regulators forward payday-loan complaints to lenders for a written response. That process can create a record of the problem and put your account details in front of the relevant parties.
A written response can help clarify what happened, but it does not ensure that money will be returned. Keep the contract and records of what you authorized, and seek independent advice if you need help understanding your options. A nonprofit credit counselor or legal aid office may be able to review them without offering you another loan.
Do not take a new advance to pay for a disputed one. You would add fees on borrowed money while the original issue remains unresolved, and the new loan does not pause the dispute.
Decide and Request Only If the Paycheck Clears
Your decision fits in three lines. Request nothing if your worksheet remainder is negative. Use a cheaper option if one covers the bill without a lump sum due on payday. Consider a short-term request only when the full payoff, fee included, still leaves rent, food, transport, and your existing debits covered with room to spare.
What a marketplace does and doesn't do
If that third line is true for you, understand what we are. NextStopLoans is a marketplace, not a lender. One form can be seen by more than one independent lender, we don't approve the loan or set the rate, and submitting information online does not guarantee loan approval. Each lender decides on its own, and you're under no duty to accept any offer you're shown.
The basic requirements to qualify are being at least 18 years old, a United States resident, having a checking account, and being employed with regular income and a pay frequency. Our service is not available in all states, and residents of Arkansas, New York, Vermont and West Virginia are not eligible to use it to request a loan. You also must not request a loan that's illegal where you live, so as an Alabama resident you still have to confirm the product itself is lawful here before you accept it.
If a lender approves you and you accept the terms, funds are deposited directly into your bank account, usually as fast as the next business day, on that lender's timeline. Treat that speed as a convenience, not a reason to borrow. Fast money that fails your paycheck test just brings the shortfall forward by a day.
Compare any offer you receive against the Alabama cap table from the start of this article. Check the advance, the fee, the total due, and the due date against your worksheet one final time. Decline terms that fail the test, even if you already filled out the form and even if the approval feels like a relief. An approval is a lender saying the loan fits its rules. Your worksheet is you saying whether it fits your life, and only one of those answers pays your rent.
If your paycheck worksheet clears with room for rent, food, and bills after the full payoff, NextStopLoans can send one loan request to multiple independent lenders so you can compare real offers against Alabama's $500 cap and 17.5% fee limit. Review each offer's total due and due date, decline anything that fails your paycheck test, and only accept terms you can repay without borrowing again.